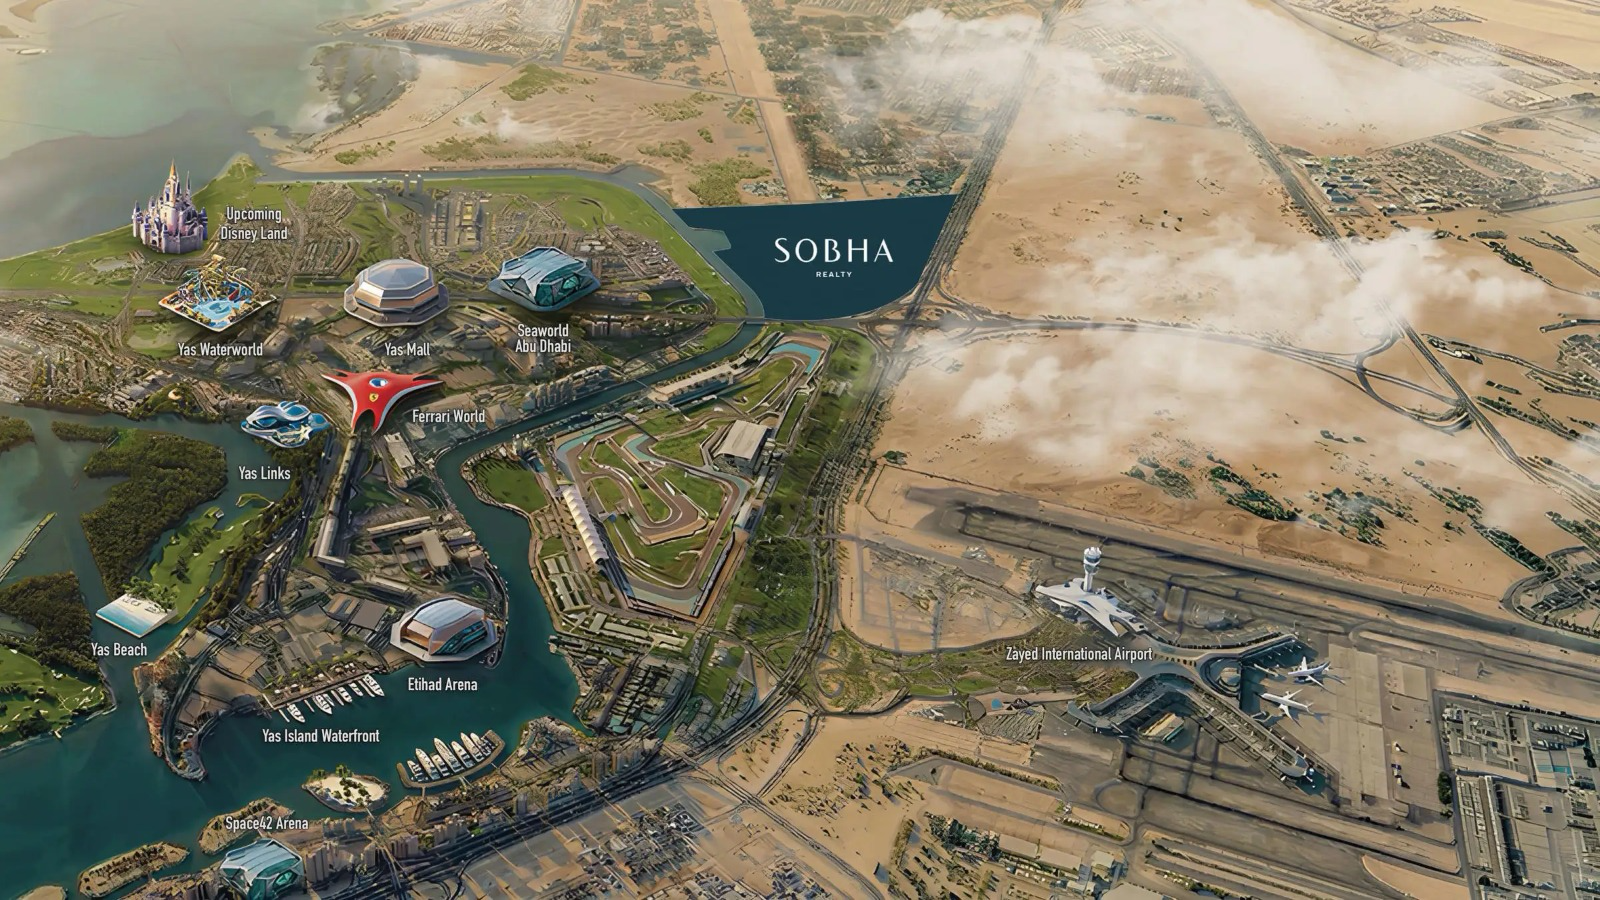

For a UK investor, buying property in Dubai is not simply a question of whether Dubai's property market is performing well.
The more useful question is whether moving some of your capital from the UK into Dubai property makes financial sense for you after considering the purchase price, rental income, ownership costs, payment structure, financing, currency exposure, UK tax position, and how long you intend to hold the property.
Dubai's market remains highly active. The Dubai Land Department recorded AED 252 billion in real estate transactions in Q1 2026, while foreign investment accounted for AED 148.35 billion during the quarter. But market activity alone does not tell a UK investor whether a particular apartment, villa or off-plan project is worth buying.
For someone sitting in London, Manchester, Birmingham, Edinburgh or elsewhere in the UK, the decision needs to be much more specific:
This guide looks at that decision from a UK investor's perspective, rather than treating Dubai property as a one-size-fits-all investment.
Why Are UK Investors Considering Dubai Property?
There is no single reason why a UK investor might consider Dubai property.
For some, the objective is to diversify part of their property exposure outside the UK. Others may be looking for rental income, a second home, a future relocation option, or access to Dubai's residential market without becoming a UAE resident first.
Payment structures can also influence the decision, particularly when buying off-plan. Instead of committing the entire purchase price immediately, some developments allow the purchase price to be paid according to an agreed schedule.
But each of these reasons needs to be connected to an actual investment objective.
For example, a UK investor looking primarily for rental income should ask different questions from someone planning to use the property as a future home.
A rental-focused investor might prioritise:
- Realistic achievable rent
- Vacancy levels
- Service charges
- Property management costs
- Tenant demand
- Resale liquidity
Someone considering a future Dubai relocation may place greater importance on:
- Community
- Schools
- Property type
- Location
- Amenities
- Future usability
So the first question is not "Is Dubai a good investment?"
It is:
"What am I trying to achieve with this property, and does Dubai offer a suitable way to achieve it?"
If you're still assessing whether Dubai fits your overall investment strategy, see our Invest in Dubai From the UK guide.
Dubai Property vs UK Property: What Are You Actually Comparing?
A UK investor naturally compares Dubai with the property market they already understand. That comparison can be useful, but it needs to go beyond headline prices or advertised rental yields.
You are comparing two different property markets, currencies, ownership environments, and tax considerations.
The questions worth comparing include:
- How much capital is required?
- What are the upfront purchase costs?
- What rental income is realistically achievable?
- What ongoing costs will reduce that income?
- How easy is financing?
- How much management will the property require?
- What currency will the investment and income be measured in?
- What UK tax considerations apply?
- How long can you realistically hold the property?
- How easy might it be to sell when you need to exit?
This is particularly important when comparing advertised rental yields. A Dubai property showing a headline yield should not automatically be compared with a UK property showing another headline yield.
The more useful comparison is:
That gives you a much clearer picture of what the investment could mean for your own finances.
How Much Money Do You Actually Need to Invest?
The advertised property price is only the starting point. Suppose you are considering a Dubai property priced at AED 1.5 million. Your analysis should not stop at converting AED 1.5 million into GBP.
You need to understand how much capital will actually be required at each stage of the purchase.
Depending on the property and transaction, this can include:
- Initial purchase payment
- Dubai Land Department and registration costs
- Developer or administrative charges where applicable
- Mortgage-related costs if financing is used
- Future payment-plan instalments
- Service charges
- Furnishing costs
- Property management
- Maintenance
- A reserve for unexpected costs
For a UK investor, there is another useful question:
How much of my available GBP capital am I comfortable committing to this investment?
That matters because an investment can look affordable based on its headline purchase price while becoming considerably less comfortable once future payments and ownership expenses are included.
You should therefore calculate the total expected capital commitment, rather than focusing only on the initial deposit.
And if you're buying off-plan, make sure you understand exactly when the remaining payments are due. A payment plan can improve cash-flow flexibility, but it does not reduce the amount you ultimately owe.
Want to Know What You'd Actually Need to Invest?
Compare the purchase price, payment structure, ownership costs, and expected rental income before deciding whether a Dubai property fits your UK investment budget.
Where Does the Rental Income Actually Come From?
For a UK investor buying a rental property in Dubai, the important question is not simply:
"What is the rental yield in Dubai?"
It is:
"Why would someone rent this specific property at this specific price?"
Rental income ultimately comes from tenants. That means you need to understand the local demand for the particular property you're considering.
Factors can include:
- Location
- Property size
- Layout
- Building quality
- Furnishing
- Amenities
- Access to transport
- Nearby employment centres
- Schools and lifestyle facilities
- Competing rental properties
- The type of tenant the property is likely to attract
A one-bedroom apartment in a location with strong professional tenant demand is a different investment proposition from a large villa aimed at families.
Likewise, two apartments in the same community can perform differently because of their building, condition, floor, layout, view, furnishing, and asking rent. For a UK investor who may be managing the property from thousands of miles away, understanding this property-level demand is particularly important.
The investment does not generate income because Dubai has tenants. It generates income because a specific tenant is willing to pay a specific rent for a specific property.
The Rental Yield You See Is Not the Return You Keep
This is one of the easiest areas for an overseas investor to misunderstand.
An advertised rental yield generally starts with rental income relative to the property price. But the amount you actually keep can be lower after ownership and operating costs.
Your calculation should consider:
Annual rent
minus:
- Vacancy
- Service charges
- Property management
- Maintenance
- Leasing costs
- Financing costs, where applicable
equals the property's more meaningful cash-flow position. For a UK investor, it can also be useful to look at that outcome in both AED and GBP.
Our guide on how to calculate net rental yield in Dubai explains the calculation in more detail.
Does a Dubai Payment Plan Actually Help a UK Investor?
Payment plans can be particularly relevant to UK buyers considering off-plan property.
Depending on the development, you may encounter structures such as:
- 60/40
- 70/30
- 80/20
- Construction-linked payments
- Post-handover arrangements
The exact structure varies by project and developer, so the current payment schedule should always be confirmed before committing.
For a UK investor, the psychological trap is straightforward:
Imagine committing to a property because the first payment fits comfortably within your current savings.
The more important question is:
Can I comfortably meet every future payment if my circumstances change?
Consider what happens if:
- Your UK income changes
- Your investment portfolio falls
- The GBP/AED conversion changes
- The property takes longer to complete
- Rental income has not started when another payment becomes due
- You need the capital for another purpose
A payment plan can spread the timing of your capital commitment. It does not remove that commitment. If you're considering this route, our guide to buying off-plan property in Dubai covers the wider process and risks.
Ready Property or Off-Plan: Which Makes More Sense for a UK Investor?
There is no universal answer. The right choice depends on what you're trying to achieve.
Ready property
A completed property gives you something tangible to evaluate.
You can investigate:
- The actual building
- Current rental levels
- Existing tenant demand
- Service charges
- Property condition
- The surrounding community
- Comparable properties
For a UK investor seeking rental income, this can make the financial analysis more concrete.
Off-plan property
Off-plan can involve a different set of considerations.
You need to assess:
- Developer track record
- Project registration
- Payment structure
- Construction progress
- Expected handover
- Future competing supply
- Location development
- Potential rental demand
- Resale options
The attraction may be a staged payment structure or access to a property before completion. But the investor is also taking on more uncertainty about the future property and market conditions.
For someone investing remotely from the UK, due diligence becomes particularly important because you cannot simply visit the development whenever you want.
How Important Is Location for UK Investors?
Location should be selected according to the investment strategy, not because an area appears frequently on property websites.
A UK investor focused on rental income may want to investigate areas with established tenant demand and a suitable balance between purchase price and achievable rent.
An investor prioritising family use may care more about schools, community facilities, space and lifestyle. Someone focused on longer-term value may instead examine infrastructure, development plans, supply, entry price and future demand.
This is why asking for the "best area in Dubai" without defining the investment objective is not particularly useful.
The better question is:
Which Dubai location fits the type of investment I am trying to build?
Our dedicated guide to the best Dubai areas for UK property investors looks at locations through different investment objectives rather than treating one area as suitable for everyone.
What Does AED vs GBP Mean for a UK Investor?
This is an important difference between buying property in Dubai and buying property in the UK.
As a UK investor, you are likely to think about your wealth in GBP. The Dubai property is priced and operated in AED. That creates a currency consideration at several points:
- When buying: GBP needs to be converted into AED.
- While owning: Rental income is generally received in AED.
- When selling: The eventual proceeds may need to be converted back into GBP.
This means an investment can perform one way when measured in AED and look different when measured in GBP.
There is no need to predict where the GBP/AED exchange rate will go. The important thing is to recognise that currency is part of your investment calculation.
What About UK Tax?
This is an area UK investors should understand before buying, not after. Owning property in Dubai does not automatically remove UK tax considerations.
Your position can depend on factors including:
- UK tax residence
- Your individual circumstances
- Rental income
- Disposal of the property
- Other income and gains
- Applicable UK reporting requirements
- Relevant international tax rules
HMRC provides guidance on foreign income, including income from overseas property:
The UK and UAE also have a double taxation convention:
UK–UAE Double Taxation Convention
The important point is not to assume that buying property in Dubai automatically means your UK tax position becomes irrelevant.
If you are a UK resident or otherwise within the UK tax system, speak with a qualified UK tax adviser who understands overseas property before making a purchase.
Looking at Dubai Property From the UK?
Get practical guidance on locations, property types, payment plans, and the key numbers to review before making an overseas property investment.
How Long Should a UK Investor Plan to Hold the Property?
Your expected holding period can completely change the investment calculation. Consider the difference between buying with an expected holding period of:
18 months vs 5 years vs 10 years.
A shorter holding period can make transaction costs, market movements, and resale conditions more important.
A longer timeframe may give you more opportunity to collect rental income and participate in changes in the property market, but it does not remove investment risk.
Ask yourself:
- Why am I buying?
- When might I need the money again?
- Could I continue owning the property if the market softened?
- Will the property still suit my objective in five years?
- What would make me sell earlier?
- Who would potentially buy the property from me?
That last question is especially useful.
An investment should have an exit strategy before you buy it, not after you decide to sell.
When Could Dubai Property Make Sense for a UK Investor?
Dubai property may be worth considering when the investment fits the investor's actual circumstances.
For example, the numbers may deserve further investigation if:
- Your investment objective is clearly defined
- You can comfortably afford the total capital commitment
- Future payment obligations are manageable
- Expected rent has been realistically assessed
- Ownership costs are understood
- UK tax considerations have been reviewed
- You are comfortable with AED exposure
- The location fits your strategy
- You have an appropriate investment timeframe
- You understand how you could eventually exit
Notice that none of these conditions depends simply on whether Dubai property prices are rising.
The specific property still has to make sense.
When Might Dubai Property Not Make Sense for a UK Investor?
There are also situations where buying from the UK may not fit your circumstances.
You may need to reconsider if:
- You need guaranteed returns
- You may need the invested capital in the near future
- The purchase stretches your finances
- You are relying entirely on future price appreciation
- You haven't calculated the property's net rental income
- You don't understand the payment schedule
- You haven't considered UK tax
- You are uncomfortable managing an overseas property
- You haven't researched the developer or building
- You have no clear exit strategy
This is particularly important with off-plan purchases.
A payment plan can make the initial commitment look manageable while leaving significant future obligations.
Before buying, you should be comfortable with the investment even if the outcome doesn't match the most optimistic scenario.
If Dubai property fits your investment objectives, the next step is understanding how the purchase actually works. See our guide to buying property in Dubai from the UK, including costs, due diligence, registration and remote buying.
10 Questions UK Investors Should Ask Before Buying Dubai Property
Before transferring money from the UK, ask yourself:
1. Why am I buying this property?
Rental income, capital growth, diversification, future use, or another objective?
2. What is my total GBP budget?
Not just the advertised AED purchase price.
3. How much do I need to pay upfront?
Include the applicable purchase and transaction costs.
4. What future payments will I have?
Especially important for off-plan purchases.
5. What rent can this specific property realistically achieve?
Don't rely solely on an advertised yield.
6. What will I actually keep after costs?
Calculate net rather than headline rental income.
7. What is my UK tax position?
Understand the relevant obligations before purchasing.
8. What does the investment look like in GBP?
Consider the impact of currency conversion on your overall outcome.
9. How long can I realistically hold the property?
Your timeframe should match the investment strategy.
10. Who could buy this property from me later?
Think about your exit before you enter.
Final Thoughts: Is Dubai Property a Good Investment for UK Investors?
There isn't a single answer that applies to every UK investor.
Dubai property can offer UK buyers access to a different residential market, rental opportunities, payment structures and international property exposure. But those potential benefits need to be weighed against purchase costs, ongoing expenses, financing, currency exposure, UK tax considerations, remote ownership and the specific risks of the property being considered.
If the purchase price works, the rental assumptions are realistic, the ownership costs are understood, the payment structure is manageable, your UK tax position has been considered, and you have a clear exit strategy, you have a much stronger basis for evaluating the opportunity.
And if those numbers do not work, a rising market alone should not be the reason to buy.
Is Dubai Property Right for You as a UK Investor?
Tell Aarika about your budget, investment goals, and timeframe. Our Dubai property advisors can help you assess suitable opportunities and the key numbers before you make a decision.